OneCasino account checks, login and responsible-play controls
 Available in GB
A OneCasino account links a player’s identity, funding details, gaming limits and withdrawal permissions. The Irish registration flow uses an email address or username, a password and a date of birth, while the account conditions allow the operator to request identity and financial documents when checks are needed. Login security, bonus eligibility and access to a cash balance consequently depend on more than simply remembering a password.
The important distinction is between creating an account and satisfying checks tied to later money movements. OneCasino’s terms mention additional verification when total deposits exceed €2,000 or on any withdrawal, and checks can also be triggered earlier. These are operator conditions, not a promise that every account follows an identical document sequence or review time.
For an Irish player, account restrictions and safer-gambling controls deserve equal attention. A single-person account rule, options for timeouts and self-exclusion, and a cooling-off period before limits may be increased affect how the account can be used over time. Understanding those controls before an account balance is tied to bonuses or banking activity reduces confusion when a transaction is held for checks.
Table of Contents
- The single-account rule also governs payment ownership
- Identity checks intensify around money movements
- Registration details become the reference record
- Limits, timeouts and self-exclusion have different effects
- A stronger login cannot replace sound account practices
- Frequently asked questions
- The checkpoints that matter after registration
The single-account rule also governs payment ownership
OneCasino’s Irish conditions describe an account for a single adult individual. Personal details have to belong to the account holder, and the rules prohibit duplicate accounts. This matters to more than the login itself: different profiles or shared banking identifiers can affect how the operator assesses ownership, fraud risk and promotion eligibility. Treating a household’s several accounts as interchangeable creates a different situation from each adult independently maintaining their own details.
Account details therefore need to remain consistent across registration and payments. The name on a funding method is expected to correspond to the player’s identity. A withdrawal may be routed to an original deposit method where possible; a non-refundable method may instead result in a transfer to a bank account. The payment destination still needs to satisfy the operator’s ownership requirements. Changing the destination does not eliminate documentary checks.
- Personal registration: the registered individual is responsible for their account and the accuracy of their details.
- One account: opening duplicates conflicts with the operator’s rules, even if different usernames are used.
- Related payment details: shared cards or other funding identifiers can have implications for promotions and account reviews.
- Funding disputes: chargebacks can trigger fraud checks and access restrictions under the terms.
It is useful to separate a rule against duplicate accounts from the narrower eligibility limits attached to incentives. OneCasino also restricts certain bonus claims by person, card, payment method and shared financial identifiers. An otherwise valid account can still fail a promotion’s own eligibility conditions, and meeting bonus playthrough does not override those conditions.
If an account becomes subject to additional review, the best evidence is ordinarily a coherent record: matching names, transaction statements, the payment instrument involved and a traceable sequence of deposits and withdrawals. A player’s account balance and payment trail are linked, so a change in funding method is not merely a cosmetic adjustment to the cashier. The rules for bonuses and forfeiture are a separate part of that same account-level picture, particularly when several balances appear on screen.
The terms also distinguish an active account from inactivity. They describe an account with a real-money balance becoming inactive after six consecutive months; that classification should not be confused with an automatic rule that all remaining money disappears on the six-month mark. Re-access, verification and withdrawal remain governed by the account and transaction terms.
Identity checks intensify around money movements
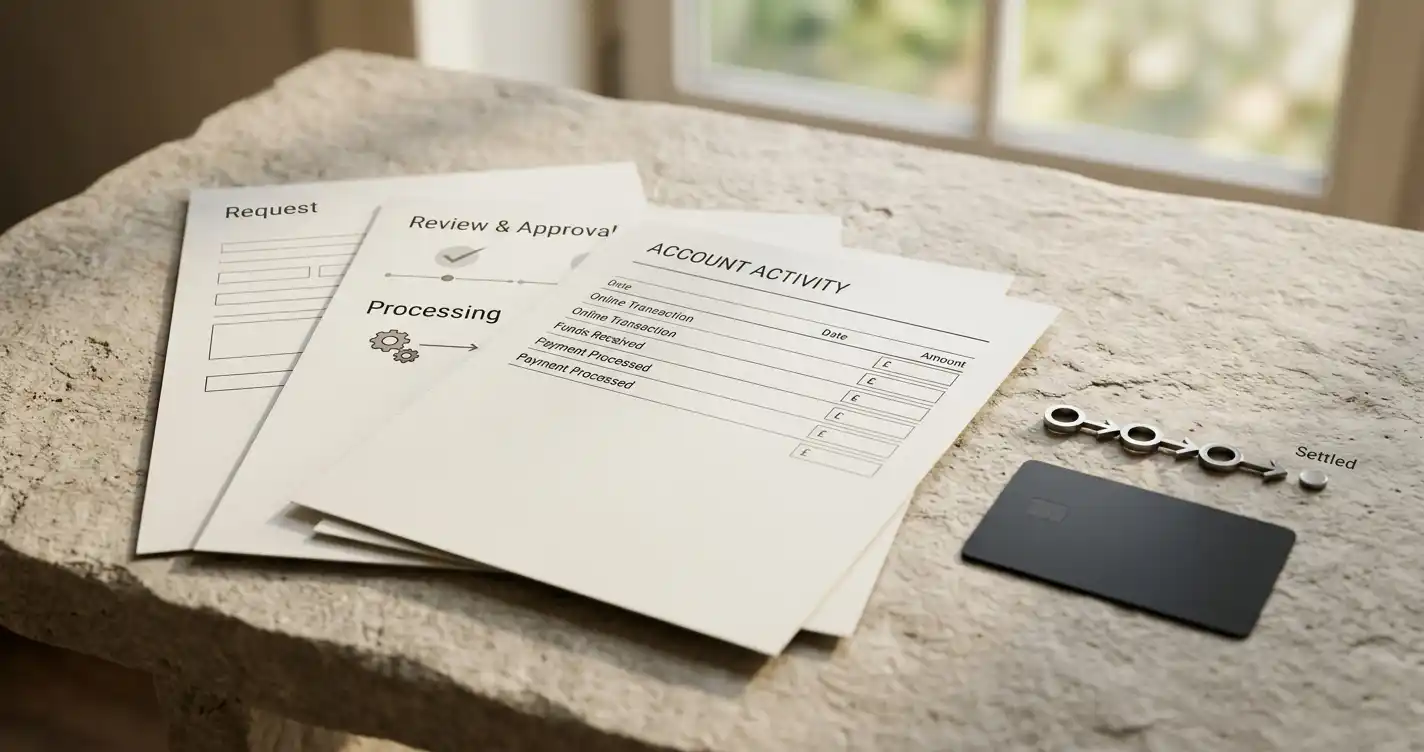
OneCasino’s terms require age and identity verification, with further information possible during the account’s lifetime. Supporting evidence can include a passport or other identification, household or billing information, payment-card details and documents showing the source of deposited money. These checks serve different purposes. A document showing a name and date of birth is not the same as evidence that funds came from an account controlled by that person.
A notable trigger is described in the Irish terms: additional verification for deposits exceeding €2,000 or upon any withdrawal. The operator may also ask for checks at other times. The deposit threshold is not an allowance to remain unidentified below that amount, while the withdrawal clause means a smaller cashout can still involve documentary review. It would be misleading to treat the threshold as an anonymous-play permission.
| Checkpoint | What it concerns | Practical effect |
|---|---|---|
| Opening an account | Age, name and personal identity | Registration data must represent the actual account holder. |
| Deposits exceeding €2,000 | Extra verification under the terms | Further identification or financial evidence can be requested. |
| Any withdrawal | Identity, funding method and source of funds | A payment may await the required checks before release. |
| Payment method review | Account ownership and financial details | Transfer destination and supporting records may be checked. |
Cashier checks and identity checks should also be kept conceptually separate. The Irish finance explanation refers to a refundable €10.01 payment-detail verification transaction used in the withdrawal workflow. The free-credit promotion describes a different refundable €0.01 bank-check transaction. They are attached to different processes; neither amount is the minimum cashout or a general account-opening fee. A third rule requires at least €10 in real deposits before the first withdrawal, again serving a different purpose.
The withdrawal stages and approval timetable explain what happens after a request is made. Verification, a decision on the request and receipt by a bank are three steps, and a delay at the first step should not automatically be interpreted as slow bank settlement. Keeping documents readable and consistent with registration details can make a subsequent request easier to understand, but cannot guarantee instant approval.
Requests for additional evidence may also arise from suspected mismatches, unusually configured payment patterns or the need to examine the origin of money. From a player’s perspective, the actionable difference is between documenting who owns the account, who owns the payment method and where the money originated. Those are related questions, but evidence for one does not necessarily answer all three.
Registration details become the reference record
The registration flow presents identity details such as a username or email address, password and date of birth. A functioning login depends on those details being accurate and maintained, especially because the same person may later need to answer an account-recovery request or prove ownership of a payment method. An invented date of birth or somebody else’s email address turns an otherwise routine verification request into a much harder problem.
OneCasino limits accounts to adults. Age information is part of the initial account record; it also underpins eligibility for promotional offers and the subsequent payment checks described in the terms. The Irish age requirement is 18+. A user should not infer that entering an adult age in a form alone completes the separate obligation to verify age when requested.
- Identity record: email or username and date of birth identify the individual associated with the account.
- Access credentials: the password and subsequent two-factor step protect entry into that record.
- Funding details: financial methods need to be associated with the same account holder.
- Verification trail: identity, address or source-of-funds records may be used to resolve later checks.
The distinction between an account profile and its funding history becomes more important when one payment instrument cannot accept a refund or payout directly. The withdrawal terms favour a return to the original funding channel where feasible but allow bank transfer in some cases. That routing decision does not transfer ownership of the casino account or authorise payment to another person’s bank details.
For account changes, a dated personal record of emails and financial transactions is more useful than a collection of screenshots of individual game results. It connects actions taken through the login with statements held by the payment provider. Where a dispute is about a withheld cashout or a balance adjustment, the transaction sequence can help distinguish a verification question from the separate application of bonus terms.
The browser-based account experience is intended to work on mobile screens as well as desktop. The same personal, banking and safer-play rules apply on either device. Switching screens or browsers does not create a new identity or alter the eligibility of a payment instrument.
Limits, timeouts and self-exclusion have different effects
OneCasino lists controls for deposits, losses, stakes and session duration. Depending on the control, the player can set daily, weekly or monthly boundaries. The important point is not simply how many controls exist: each measures something different. A deposit limit addresses money brought into the account, whereas a loss limit focuses on financial outcomes; a session control addresses time spent playing. Combining limits may cover different risks that one broad budget setting misses.
There are also timeouts for 1, 7 or 30 days, plus timed or open-ended self-exclusion. A timeout and a permanent or open-ended exclusion should not be treated as interchangeable buttons: one creates a defined pause, while exclusion is designed for a more substantial interruption of access. For a player experiencing loss of control, self-exclusion and external support offer protections that an ordinary bet-size preference does not.
| Control | Purpose | Why it matters |
|---|---|---|
| Deposit limit | Amount funded during a period | Sets a boundary on incoming gaming funds. |
| Loss or stake limit | Financial exposure from play | Addresses costs that a deposit total may not capture. |
| Session control | Time spent on the site | Creates awareness of prolonged play. |
| Timeout | Pause lasting 1, 7 or 30 days | Interrupts play over a defined interval. |
| Self-exclusion | Timed or open-ended exclusion | Blocks access under the selected exclusion conditions. |
A particularly consequential condition is the seven-day cooling-off period OneCasino applies to raising or removing limits. A chosen limit constrains play, while a later request to lift the restriction is subject to a seven-day cooling-off period. The friction is intentional: it reduces the chance that an impulsive decision during a losing session will undo a previously chosen boundary.
For example, a player may have enough cash in the account to continue playing yet still be constrained by a stake or session limit. That is not a payout defect or a change in available funds: the control governs activity independently of balance size. Likewise, waiting out a timeout does not imply the account should immediately increase a previously selected spending limit.
Responsible play requires that these boundaries be established without relying on hoped-for winnings to finance future sessions. Gambling can cause financial harm; a repeated pattern of increasing limits, borrowing for play or chasing losses is a reason to stop and seek support. Irish confidential help is available from Extern Problem Gambling at problemgambling.ie, 089 241 5401, and Gambling Care at gamblingcare.ie, 1800 936 725.
A stronger login cannot replace sound account practices
The OneCasino login workflow displays two-factor authentication options through SMS or email. These provide an extra step alongside the usual password. Their usefulness depends on protecting the linked phone number or email account: someone who can access both the password and the recovery channel may be able to defeat an apparently separate checkpoint.
Good account hygiene also means using unique credentials and keeping financial identifiers private. A casino password should not be shared between family members simply because they use the same device. Under the one-person-account rule, that habit would also blur who initiated a transaction. The distinction matters when support needs to examine logins, payment ownership or an account action attributed to its registered owner.
OneCasino’s terms prohibit disguising location through IP or device-location masking, alongside automated or advantage-play software and misuse of bonus mechanisms. These are contractual restrictions and should be read as such; technical workarounds to hide account circumstances can place withdrawals and promotional balances at risk. A normal mobile-browser session remains subject to the same rules as a desktop session.
Chargebacks are another common source of friction. A disagreement with a card issuer about a deposit may produce a financial reversal, but the operator’s conditions reserve account suspension, blocking and anti-fraud checks when chargebacks occur. A payment disagreement therefore should not be mistaken for a routine password-recovery problem or solved by simply opening another account.
For questions tied to an existing account, OneCasino provides live chat and email support including [email protected]. Keeping the registered email, request details and transaction documents aligned improves the clarity of correspondence. Complaints are a different channel from ordinary troubleshooting; readers dealing with a dispute should preserve the relevant records rather than rely on verbal summaries of an earlier conversation.
An account is ultimately the point where time limits, eligibility rules, financial evidence and access security meet. The most durable protection is a consistent identity record and limits that remain effective when play becomes stressful, rather than repeated changes of device, method or credentials to resolve a restriction.
Frequently asked questions
Does OneCasino check identity before withdrawals?
Yes. The terms allow identity checks on any withdrawal, and further checks when deposits exceed €2,000 or when the operator needs additional supporting evidence.
Which two-factor channels are shown?
The login workflow presents two-factor authentication through SMS or email.
How long is the cooling-off period for raising limits?
The account terms apply a seven-day cooling-off period to increases or removals of limits.
The checkpoints that matter after registration
OneCasino accounts carry several overlapping rules: registration identifies one adult, payment activity can trigger identity and source-of-funds checks, the login can require a second factor, and limits can restrict play independently of balance size. The practical sequence is to keep a consistent identity and transaction record, distinguish account verification from cashier processing, and treat timeouts and the seven-day delay on loosening limits as substantive safeguards. These controls do not guarantee any individual withdrawal outcome, but they explain why an apparently straightforward request may involve more than clicking a cashout button.
Read next
Written by the editors at Onecasino-ie.net.