OneCasino withdrawals: approvals, checks and settlement
 Available in GB
A OneCasino withdrawal involves a request decision, account checks, transfer processing and final bank posting. For an Irish account, the first cashout has a specific real-deposit prerequisite, while operator review and actual receipt follow separate timelines. Treating those stages as a single instant payment can lead to incorrect assumptions about what a cashout status means.
The conditions deserve particular attention when the balance includes a deposit bonus, a funding method cannot accept refunds, or the operator asks for more identification. A real-money deposit of €10 before the first withdrawal, the separate finance validation of €10.01 and an actual withdrawal amount describe three different matters. None substitutes for the other.
OneCasino sets out a five-working-day decision policy and describes further operational steps in its withdrawal help. Their purpose is to distinguish request handling from delivery of money, not to provide a personal guarantee of speed. Each stage has its own check and receiving party.
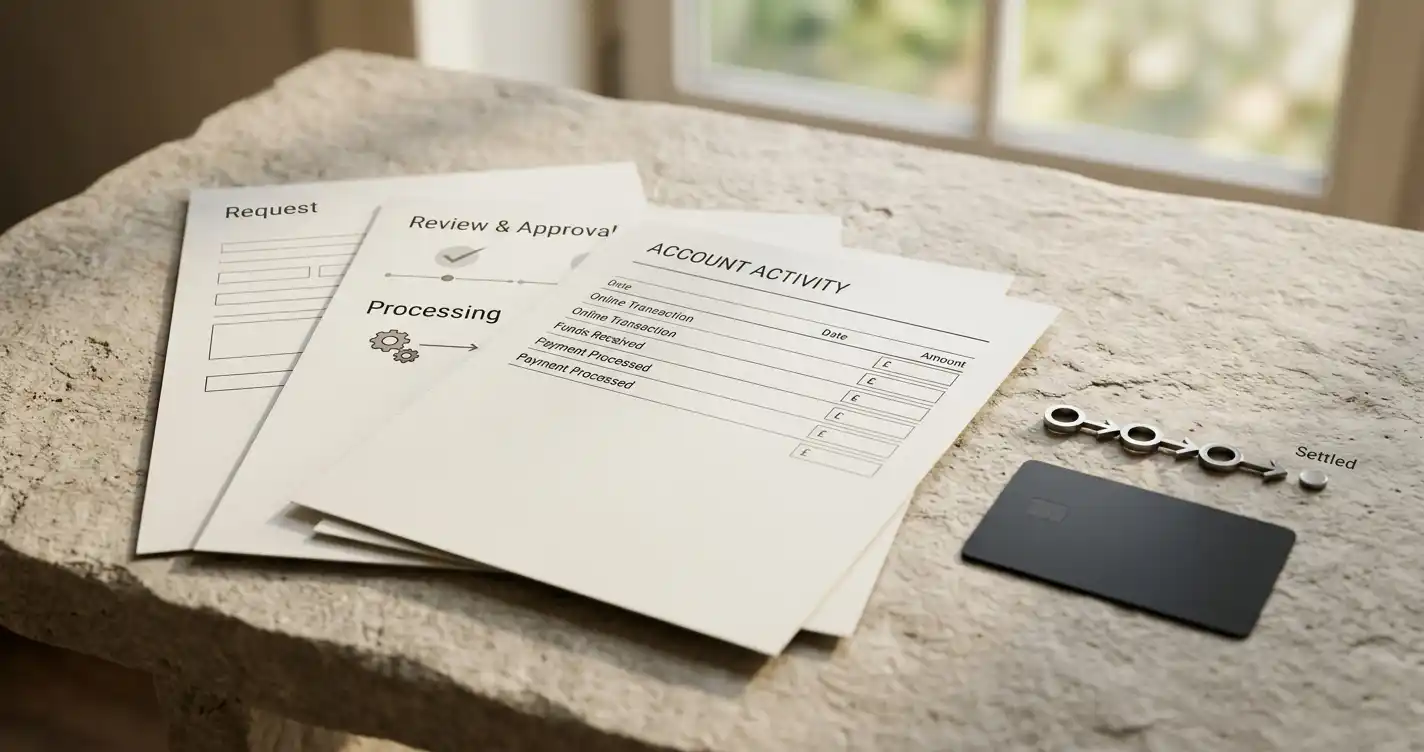
Table of Contents
How a cashout finds its destination
OneCasino’s Irish terms favour returning withdrawals to the method used to fund the account, where that method can receive the transfer. The account holder’s name must match the payment details. For a customer who funded with a card or electronic wallet, the path out therefore depends on the receiving capability of that product, the original transaction and the ownership records attached to it. A deposit that was accepted successfully is not a guarantee that the same rail can receive cash.
Where the original method is non-refundable or cannot accept the return payment, the casino can use a bank account instead. That creates a practical distinction between source-of-funds evidence and destination-of-funds evidence: the initial payment establishes where the money came from, while the bank details identify where eligible funds would be delivered. Different records can be requested for those two purposes, even when the person named on them is the same.
For example, paysafecard is listed as a funding route for the Irish service, but its inclusion among deposits does not turn a prepaid voucher into a general-purpose receiving bank account. Skrill and payment cards also have product-specific return features. The Irish payment-method overview lists the funding routes without presuming a corresponding withdrawal channel for every entry.
- Original route: a permitted repayment to the original source, with the account name matching.
- Alternative route: a bank account where the original funding method cannot receive the transfer.
- Ownership check: confirmation that the financial account and the OneCasino account belong to the same person.
- Provider step: the receiving institution’s own process after a payout is executed.
A useful way to understand a delayed payment is to identify which of these steps is active. A request for bank details can be a routing issue; a request for a passport or proof of address belongs to identity checks. Neither automatically establishes that the casino has approved the cashout or sent funds to a payment provider. Keeping the stages apart prevents a transaction from being treated as completed merely because a withdrawal request has been entered.
It also matters which currency is being settled. Irish balances are in EUR. If the receiving bank or card account operates in another currency, conversion charges or margins may affect the final amount outside the casino balance. That distinction becomes especially important when reconciling the amount requested with the amount actually credited.
What fees and conversion can change
The OneCasino finance information describes deposits and withdrawals without casino charges, but its terms reserve the right to apply a fee displayed when a cashout is made. The practical position is conditional, transaction-specific charging, rather than a blanket promise that every route costs nothing. Any disclosed casino charge belongs to the requested transfer; a bank’s exchange rate or external payment-provider fee belongs to a separate layer.
The distinction is material for Irish customers using EUR balances. A €-denominated balance can still be received through an account whose provider applies currency conversion. Even where the casino’s own charge for a particular withdrawal is zero, the receiving bank’s exchange calculation can produce a different final figure. Conversely, a transfer that triggers a stated cashier fee should be understood in its own right, not folded into a supposed exchange-rate adjustment.
A withdrawal record can be read as a sequence of amounts: the requested euro balance, any fee shown at the cashier, the transfer actually sent and the funds posted by the bank or wallet. This is a reconciliation method, not a promise that OneCasino will supply a particular fee statement format. If there is a discrepancy, identifying the stage at which the amount changed is more informative than inferring that the whole difference represents a casino charge.
- Keep the withdrawal amount and currency separate from the underlying original deposit.
- Read the transaction-specific cost or fee notice at the withdrawal stage.
- Distinguish any operator deduction from later bank or payment-provider conversion.
- Use the receiving-account record to establish the value finally credited.
A payment cancellation, reversal or disputed card transaction is also different from a processing fee. The casino terms address fraud controls and chargeback consequences separately; those provisions can trigger account review and affect the ability to complete withdrawals. A cashout condition should therefore be interpreted together with account eligibility, rather than reduced to a single percentage cost.
Identity checks at the moment of withdrawal
Under OneCasino’s terms, withdrawals are a specific trigger for extra customer checks. The operator can request an identity document, proof of address, payment-ownership records or material explaining where the money originated. It also describes additional verification for deposits exceeding €2,000, alongside its broader power to request information where needed. A previously successful login or deposit does not replace the withdrawal-stage checks.
The casino’s finance material separately describes a refunded €10.01 payment-details validation before processing a withdrawal. That process concerns verifying financial information. The much smaller refundable €0.01 bank check described in the no-deposit promotion serves a different offer-specific purpose. Neither figure is a published general minimum withdrawal, and combining the two into a supposed universal cashier charge would be misleading.
The purpose of each document is easier to understand when divided into identity, residence, account ownership and source of funds. An identity card can support name and age verification; a bank statement may link a payment route to the account holder; evidence of income or financial activity may relate to source-of-funds controls. These documents are not interchangeable, and a request for one does not mean all the other checks have been completed.
The account verification and limits guide explains registration details, two-factor login choices and the circumstances under which OneCasino may require further records. A customer using a shared device still has an individually registered account, and the account rules prohibit duplicate personal accounts. That account-ownership principle remains relevant when someone is trying to pay into or withdraw from a differently named bank account.
- Identity: name, date of birth and documentation where requested.
- Payment ownership: proof that an original funding or receiving account belongs to the casino customer.
- Source of funds: material supporting the origin of deposits or gambling funds.
- Account consistency: details that correspond with the registered OneCasino account.
Withdrawal eligibility can also be affected by bonus conditions or suspected misuse. The terms discuss low-risk play, automated advantage-play software, fraud investigations and chargebacks. These are separate contractual reasons a withdrawal may enter further review. A document check cannot by itself remove bonus restrictions, just as completing a bonus wagering condition does not remove financial-identity requirements.
The real-deposit condition before a first withdrawal
OneCasino requires a customer to have made at least a €10 real-money deposit before the first withdrawal. This is a prerequisite tied to the account’s deposit history. It is not a stated minimum cashout, and it does not mean that a request for €10 is automatically eligible. The required real deposit and the requested cashout are different transactions with different purposes.
The terms also allow the operator to require deposited funds to have been wagered at least once before withdrawal. That condition concerns the use of deposited money, and it should be separated from promotional wagering requirements. For example, a deposit match can impose its own bonus playthrough and game-contribution rules. Meeting a one-time deposit-wager condition is not the same as completing a separate 35× promotion, and neither is equivalent to identity approval.
A reader considering a balance composed of deposits, winnings and bonus entries should keep those categories distinct. A euro figure shown in the account does not establish whether all components have the same withdrawal rights. Bonus credit can be reduced or removed when a withdrawal is requested under applicable promotional terms. The amount eligible for payment depends on the underlying transaction and offer conditions, rather than the size of the displayed balance alone.
| Condition | What it concerns | What it does not mean |
|---|---|---|
| €10 real deposit | Prior funding needed before the first withdrawal | A €10 minimum withdrawal amount |
| Once-wagered deposit | Possible use-of-funds requirement under the terms | Completion of any separate bonus playthrough |
| €10.01 refunded validation | Payment-details checking in the finance information | A permanent flat withdrawal fee |
| Identity and ownership documents | Eligibility and financial-account checks | Proof that a bank has already received a transfer |
Casino Guru describes unlimited total EUR withdrawals in its independent profile of OneCasino. That category is about an overall withdrawal-cap assessment, not permission to submit unlimited amounts in one request, bypass review or demand unlimited immediate settlement. The applicable transaction instructions and account checks remain relevant to individual requests.
The most useful reading of the first-withdrawal condition is therefore narrow: it establishes what funding history the account must have. It does not set the later processing timetable, waive verification, determine the receiving bank or promise that promotional funds can be withdrawn without meeting their separate restrictions.
Decision, processing and bank arrival run on different clocks
OneCasino’s terms say a withdrawal request should be approved or denied within five working days. This is a timeframe for the operator’s decision, not a promise that money arrives in a bank account within five working days. Once a request has been examined, the payment still has to be executed and posted by the receiving institution. Account-document requests and processing schedules can affect the actual sequence.
The withdrawal-help information describes review windows from Sunday to Thursday, 21:00–23:00 CET, with processing the following morning. It also describes receipt taking up to 48 hours during business days after processing, and weekend delays that can extend arrival until Monday. The finance information expresses an expectation of bank settlement within two business days, conditional on processing. These are OneCasino’s stated timetables, not independently measured transfer speeds or a combined guaranteed deadline.
| Stage | Reference point | Time or constraint |
|---|---|---|
| Request decision | Approve or deny a submitted withdrawal | Within five working days under the terms |
| Scheduled review | Help-centre review activity | Sunday–Thursday, 21:00–23:00 CET |
| Processing | Transfer execution after the review | Following morning in help guidance |
| Posting | Receiving bank or payment account credited | Up to 48 hours during business days after processing in the help text |
The review window and processing description should not be used as a countdown from the moment the player presses a withdrawal button. A submission may be subject to identity checks, a different part of the service schedule or a weekend. Similarly, adding all the displayed time figures together would imply a single end-to-end performance rule that the terms do not establish.
- Identify whether the request has been submitted, reviewed or formally decided.
- Separate any missing documentation from the operator’s execution of the transfer.
- Record the point at which a transfer is actually processed or sent.
- Distinguish the final bank posting from both the approval message and the processing entry.
A withdrawal marked as approved is not automatically a bank transfer marked as received. If money has not appeared after processing, the relevant information changes: the receiving method, transaction reference, provider availability and any intervening business days become more useful than a restatement of the original request time. Understanding that separation also prevents a delay in identity review from being mistaken for a bank settlement failure.
Frequently asked questions
Is €10 the minimum cashout?
No. OneCasino requires at least a €10 real deposit before the first withdrawal. That deposit prerequisite does not define a minimum withdrawal amount.
When does the five-day period end?
The five-working-day period in the casino terms concerns approving or denying a withdrawal request, not the arrival of money at a bank.
Why might money reach the bank later?
Payment execution and bank posting are separate from approval. OneCasino describes business-day posting periods and possible weekend delays after processing.
Separate approval time from money arrival
OneCasino’s withdrawal rules bring together several different obligations: a real deposit before the first cashout, eligibility checks at account level, the possibility of transaction-specific fees and a payment route that must return to the correct account owner. None of those obligations should be translated into a single platform-wide minimum or a promised number of hours between requesting and receiving money.
The most consequential distinction is between the operator approving a request and the receiving institution crediting funds. The stated five-working-day policy addresses the former; the help and finance timetables describe later execution and banking stages. A reader who separates those events, reconciles euro amounts and identifies the precise verification request can make sense of the process without assuming every cashout follows an identical route.
Read next
Prepared by the Onecasino-ie.net editorial staff.